Showing posts with label Recession. Show all posts

Friday, April 17, 2009

Unfair taxes?

First I would like to say that I am proud to live in a country where people can hold demonstrations or rallies to have their voices heard even if it is differing from my opinion.
Two days ago,
tax day, there were rallies across the country for people who believe they are being unfairly taxed.  This is interesting considering our current tax systems have been been benefitting the rich, not the poor who need it most, but I digress.  

Now, I am certainly not rich, but I can sympathize with the notion of not wishing to have more money taken out of my paycheck or given to the goverment when I file my taxes.  That being said, if five more dollars a paycheck could save programs that help vulnerable children or get one more homeless person off the street then I am for it.  I think we all should do our part to help the community around us, hence why I am such an advocate for volunteering.  Sure, people could just donate money to important causes or volunteer to help these causes and we may not need higher tax rates, but most people generally do not volunteer or donate money to help out the local community.

I don't think of myself as a socialist, rather I want to help out those who are less fortunate than myself.  If the increase in taxes go to save a persons job, again why is this such a bad thing?  Those are my thoughts, but I always like to hear others.


*This increase in taxes may not go to help these municipal services, but that is why I also think it is important to have your voices heard and talk to your local representatives about your opinions or attend rallies to peacefully demonstrat your views.  

Thursday, March 5, 2009

Spirit of Service is Hiding Something


OK, so your time has freed up a bit because things are slow at work and your getting a little nervous that your job might not be there tomorrow.

Experts say the leading cause of depression and anxiety during this recession is lack of meaning. People who's schedules were jam packed now have free time and are contemplating (while procrastinating and worrying) how they should spend it. We have an answer that is both meaningful and productive...

Volunteer, serve on boards, network, make friends, get off the couch, go out for a drink after work, try a new restaurant.... you see where I'm going with this.

Come tonight to Spirit of Service from 6-9pm at M.J. O'Connor's by the Park Plaza Hotel.

Mingle with others like yourself looking to volunteer, eat, drink, and visit the tables of over 30 nonprofit organizations. Stop in or stay the whole 3 hours; bring your resume or leave it at home; wear your dancing shoes, a suit, your workout clothes --- just come!

All of the organization you see in the picture above (along with some others that will be floating around) will have volunteering opportunities in the Boston area. Some will also be looking for people to serve on their board. I'm sure at least one of these organizations will inspire you.

Sunday, March 1, 2009

I want to spend money

I'm extraordinarily lucky for numerous reasons. I'm safe, happy, and healthy for starters. And to put the icing on the cake, I'm employed doing a job that I actually enjoy.

Every morning on my way to work at this job that I enjoy, I listen to news stories about the economic woes. People are unemployed, and even if they have jobs, they aren't spending money. What can I do to help? Well spend money, clearly. I'm not exactly rolling in dough, and I was raised by very frugal parents. But my boyfriend and I do go out to eat once or twice a week, we're going on a 12 day vacation, we're doing our part.

But I decided I wanted more. It was time for me to make a big purchase - my very first TV. After all, I'd be helping the economy, and prices are pretty danged good right now...

I'm not a martyr with no screens in the house. I'm currently using the TV my boyfriend bought with his snow shoveling money when he was 12 years old. It's 19 inches - not too shabby! - but it is 15 years old. Prior to that, I was using my grandmother's old 17 inch TV, even after it was flooded in 8 inches of water (the sound is a little fuzzy now). My DVD player is one of the first ones that ever came out, and came free courtesy of my dad's previous job. I also have a 3 year old laptop (with a line down its display), my work laptop, an iPhone, and a Wii from Craig's List.

But man oh man, I wanted a flat screen LCD TV, at least 32 inches, 1080p, and a decent contrast ratio.

But I couldn't find one anywhere, at least in my price range. It's been a month. Target hasn't gotten a shipment of TVs since before the Superbowl. BestBuy only has humongo TVs in stock way out of my price range Kmart didn't have any nice ones. Circuit City's going out of business "bargains" were nothing of the sort. Walmart (yes I even tried there) was way out of stock.

I wanted to spend ~$800, and can't find anyone to sell me a decent flat screen TV that hasn't gotten terrible reviews! There's three possibilities:
  1. People are continuing to spend money they don't have, this time on TVs.
  2. The economy's not actually that bad, at least in the Boston area.
  3. The economy's so bad that TV manufacturers stopped making and shipping TVs, and/or retailers have stopped ordering stock for their shelves.
I tend to think it's #3, but likely it's a combination of all three factors.

For now, I'm just sitting on the $800 bucks. I'd rather have the TV, esp. since my ING DIRECT savings account is just getting 1.35% interest right now. I could go online to get it... but I tend to think I'll put in the order and it won't be fulfilled!

Perhaps instead of sitting on the $800, I should invest it in one of these TV companies. What do you think?

Related Posts: Sock it to the Holidays; Emergency Christmas; Penny Pinchin' Times; MEFA: down and out
This communication is for general informational purposes only and is not intended to constitute investing advice or a recommended course of action.

Monday, December 22, 2008

Sock It To The Holidays! --- A little humor

It's been icing, it's been snowing, and all we hear about is how our economy is in trouble. Watch (and listen) to these "wise socks" tell you how it is. It's a little TGIH (Thank Goodness It's the Holidays) for you this Monday morning!


Related Posts: Ice Storms and How you can help; Penny Pinchin' Times; Don't forget about your pet; It's still the economy, stupid
Video shared with me by my godmother Jeanne. Thanks!

Thursday, November 13, 2008

Read the paper!

This is Casey's mom blogging at the OYFP event at Parris - the bar above Ned Devine's at Fanuel Hall. It was hard to find because I didn't know where I was going because I'm not that hip.

When I saw the great photo for this event in the G section of the Globe at 7 am as I turned towards the Bridge column, I immediately called Casey. Conveniently, her phone number was listed in the event description.

In acting before thinking, I realized that it was only 7 am, which explained why Casey sounded like she had just woken up.

"My alarm was about to go off," Casey said, I think to make me feel better.

I wanted her to see the article in the Globe.

I wanted her to buy a copy of the Globe.

I want every 20-something to buy the Globe regularly if they want the Globe to continue as a brand.

But 20-somethings don't buy newspapers, much less have time to read them. When you do, it's online, for free.

The first newspaper was started in Germany in the 1500s to report on how the government was spending tax revenue and if it was going to raise taxes! We need journalism as the fourth branch of government, to comment on our policy makers, to inform, to educate, to entertain.

The Internet is killing journalism. Newspapers used to make a killing on classifieds. It was the only way to buy and sell things and post and find jobs. Now we can do it more efficiently online.

Should newspapers go the way of General Motors, which was once the biggest company in the world? I think GM considered itself invincible and had license to build inane vehicles like the Hummer. Now they're in trouble and I have no sympathy.

Are newspapers in the same trouble? For centuries, newspapers have been the paper of record. We have relied on them as institutions to provide balanced information and commentary on our society.

--Casey's mom, a former journalist

Well, what do you think? Are newspapers in trouble? Some are certainly trying to re-invent themselves with an online presence... but are having limited success. Remember BostonNOW? Yeah... it's gone. Not because it wasn't profitable, but because the corporate parent decided it was a risk they couldn't take. So. Are newspapers going the way of the typewriter - gone, but not forgotten?

-- Casey

Related Posts: BostonNOW is no more; More News about News; Boston Globe and OYFP; We're good enough for.. (1) and (2)

Read Casey's Mom's blog about living the green life, and the mysteries of chickens at Cluck-Cluck-Here.blogspot.com.

Thursday, October 9, 2008

Charitable Giving in 2008 - What's the outlook?

Banks are failing, foreclosures are abundant, we've officially been in a recession for a few months now, we're still at war spending billions... the outlook is not good, especially for people's pockets.

Does that mean, though, that non-profits are in trouble? If my pocket is empty[ier] than before, chances are that I'll be giving away less. In fact, for a lot of people, that might be where the funds are cut first.

Ug. Not what any of us associated with non-profits would like to hear. Who wants to think about kids with cancer who might not have housing because donations are down, or that the banks of the Charles River become even more trash covered since there are no funds to get supplies for volunteer cleaners?

So maybe you can't afford to donate your hard earned cash. That doesn't mean you can't give. Instead, try the following:
  • Donate clothes that no longer fit (no honey, you're not going to fit into those jeans from college)
  • Donate your pet supplies that your pet treats with disdain or perhaps have outgrown since their adorable baby animal years
  • Volunteer with friends for a few hours at your local soup kitchen, with one of OYFP's partners, or with YAVA this Saturday
  • Take the a UNICEF box around with you to collect change when you go trick-or-treating this Halloween (adults can trick or treat too!)
  • Run a coat drive at your workplace
  • Donate blood! Plus you get some yummy snacks afterward.
There are things you can do to help without spending money. People need your help now more than ever!

Related Posts: Don't forget about your pet; Sock monkeys for charity; Increasing Food Costs; It's the economy, stupid; What is this credit crisis you speak of, and why do I care?; An economic recovery plan, in a cup; The R-Word; Penny Pinchin' Times
Photos courtesy of Nice Diver

Thursday, September 18, 2008

Penny Pinchin' Times

Perhaps if you live under a rock or in a cave, or don't watch TV, listen to the radio, read magazines or newspapers, walk down the street, or talk to anyone, you haven't heard that the economy is in trouble. Investment banks are collapsing left and right, there's not much available credit, the US dollar isn't worth very much.

What does that mean to you? Well, aside from making that planned trip to Europe exorbitantly expensive, it means you're suddenly going to find that your money isn't going that far. Two interesting bits I heard on NPR:

Salaries have not been keeping up with inflation. So, to substitute, people have been using credit of all types - home equity, credit cards, etc. That's sounds like a recipe for disaster.

We're in the worst economic times since the Great Depression, at least according to one commentator.

Remember those times in the 1930s? No, me niether. But I remember hearing my grandmother talk about it. She used to search in the couch cushions for loose change in order to be able to take the trolley to school. Until the day she died, she re-used everything, and her favorite places to shop were estate sales and garage sales. For a special treat, she'd take a look at the clearance rack at Marshall's. And all things considered, my grandmother and her family had it pretty good during the great depression - her mom was a physician.

I don't think most of us are quite at that level yet. To keep more of your money around, here three of my ideas for what you can do to save a little, but still have fun:

1. Go out to eat less. When you get the urge to go out, have just an appetizer and drink at the bar. Chances are that will be filling enough. Alternatively, order the food but not the liquor and you'll save a bundle (in both $$ and calories). My favorite way to eat new foods is to host a potluck! No, I'm not a mom, I'm a twenty-something who happens to love potlucks. Try it for yourself, it's fun.

2. Make gifts for birthdays and the upcoming holidays. You don't have to be all Martha Stewart to give something nice. For my friend's recent wedding, we all wrote memories and things we loved about her on pretty slips of paper, and put them in a decorative jar. Cost was minimal, and she absolutely loved it. Alternatively, you could pick up a frame at a garage sale, spiff it up with some spray paint, and put in a photo of you and the giftee or a meaningful quote of some sort.

3. Take public transportation, walk, or ride your bike instead of driving your car or taking a cab. You'll prevent road rage, avoid accidents, and save the earth, all while saving your moneys. Yes, you will have to budget in a little extra time, but it could be well worth it.

All these small behavioral changes can add up - try them, and you'll see!

What are some of your tips for pinching a few pennies?
Photo courtesy of LizWhitmire.

Thursday, August 7, 2008

MEFA: Down and out

A few months ago, we wrote about how MEFA (the non-profit Massachusetts Education Financing Authority) could not find any financing to provide low interest college loans to Mass state residents. Their goal for the year was to raise $600 million from private financing, which they would then lend out to college students.

Well, things didn't improve, as you might have guessed. MEFA raised no money, and has no low interest loans to offer. Governor Patrick is trying to raise funds for the organization by getting the Massachusetts state pension fund to buy $50 million in MEFA bonds. The effort, though noble, will not come close to the $600 million they were shooting for, even if the bonds are purchased by the state.

What does this mean? Fewer kids may be able to afford college, or if they do go, will come out with much larger debt loads. They'll enter the work force (if they can find a job) and be working their butts off just so they can make their loan payments.

"Wait," you say, "I already am doing that."

Sure you are... but it's going to be worse for those coming after us. My siblings and I chose to go to state schools, and had very little debt due to our parents' diligent saving and our hard work over summers and during the school year. However, the price of state schools is increasing, and the number of students who want to attend the more affordable University of Massachusetts is skyrocketing. The more kids that want to attend, the more competitive admittance is. That leaves students who may not have had the best grades in high school (but who have plenty of potential) with fewer options.

So where does that leave us? State schools are more expensive, less well funded (which may impact the quality of the education), and more competitive. Students can't get affordable loans.

Geez. I've pretty much talked myself into a corner. I guess I should start saving for my theoretical kids' theoretical college educations... unless you have an alternative solution...?

My sister Kristen (on the left) learns how to be an artist at UMass Dartmouth


Tuesday, June 3, 2008

Don't Forget About Your Pet

Some would say that our economy is currently in recession. Whether you agree with it or not, you will have heard that the economy outlook is not so good for 2008. With people concentrating on making payments to their adjustable rate loan rate they may not have money to pay for food for their beloved pets.

Some pets even become abandoned, according to Brian Adams, Spokesman for the Massachusetts Society for the Prevention of Cruelty to Animals. Mr. Adams continues to say, "We've seen dogs that have either been chained up outside or left in the yard when the people have left, we've seen cats who are just set free''.

If you own a pet and can no longer pay for their food or shelter here are some places you can take your pet so they can find a new loving home.
    • Dedham branch: (781) 326-0729
    • Lower Cape Cod branch: (508) 255-1030
To find other shelters in your area, go to petfinder.com. Out in your zipcode on the left hand side to search for Animal Welfare Groups.

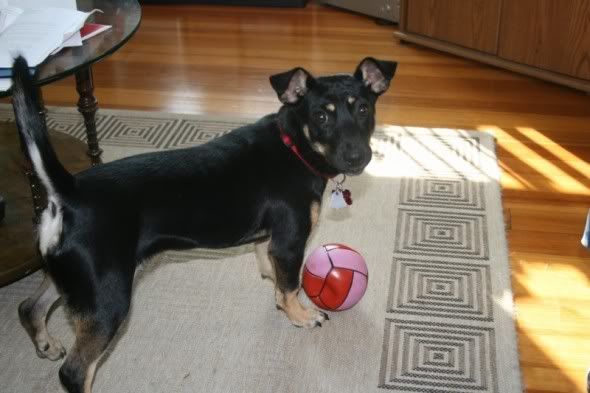
If you also have the time and resources available may I also suggest to use petfinder.com to find the pet you are looking for. That's how I found my rescue dog, and couldn't be more happier with her. I mean, who is going to say no to that face!

Related Posts: Moose Plays Dead; Recycling Dog; Sock monkeys for charity;It's the economy, stupid; What is this credit crisis you speak of, and why do I care?; An economic recovery plan, in a cup; The R-Word; Penny Pinchin' Times

Photo Coutesy of: Moi

Wednesday, March 19, 2008

It's still the economy, stupid.

James Carville, former political strategist for Bill Clinton during his presidential campaign against George H.W. Bush, originally coined the term “The economy, stupid”.

At that time, George H.W. was the strong favorite in the race for the White House until the (Bill) Clinton campaign adopted messaging that echoed the public’s fears of the economic slowdown caused by the stock market collapse on Black Monday in October 1987, and proven in the actual recessions in 1990 and 1991. Why was George H.W. Bush way ahead early in the polls? Because he was seen as having more experience with national security.


It's still the economy, stupid. "From concerns about the economy and the war in Iraq to the perennial topics of Social Security and the health care system, a range of issues are guiding this year's presidential race," CNN.com goes on to list the issues and show the poll results. Many of the polls suggest that the most important, if not the main, issue Americans care about is the economy.


So, we know the economy is a concern and we know the credit crisis is almost certainly the biggest concern lately. But, what exactly is the problem? The problem is that we don’t know where the problems are.


As the Economist put it: “There is still vast uncertainty about how much toxic debt remains, and who owns it. This has led banks to hoard money and call in loans.” Until the bad investments are uncovered we don’t know of their existence and banks will remain very conservative. This unknown has created a panic on Wall Street and caused severe cutbacks, speculation and major stock fluctuations over the past few months.


One thing is certain, confidence is key and the current uncertainty will certainly lead to further bumps in the road. Hold on and strap in because its still the economy, stupid.

Monday, March 10, 2008

What is This Credit Crisis You Speak Of? And Why Do I Care?

I thought it might be useful to follow up on Casey's post regarding the credit crisis and its recent impact on the student loan market. The events of the past nine months have been a sobering statement about what it means to be able to borrow money. From the most complex transactions at the largest banks in the world to your grad school loan or home mortgage, all the way down to the woman in rural Vietnam taking out $35 for a six month loan so that she can buy a pig, the wheels of economic mobility are greased by - better yet, completely stuck without - someone being there to lend you the money.

We borrow money every day: from the credit card company when we go to the grocery store or the mall, from Dell when we buy a computer, from the dealership when we buy a car... the list goes on. We also lend money every day.... to the banks where we keep our savings. They pay us a little interest on that money so that they can lend it out to other people for their home mortgages, cars, etc. Importantly, banks also raise money by selling off their loans to investors in packages (think of it as putting 1,000 loans in one box and shipping it to someone else), so that they can use that money make more loans.

What happened that messed everything up? Well, at its core, borrowing and lending money is not just a legal contract, it's a social contract, a chain where all the links in the chain must be solid in order for the system to work. If someone takes out a loan they can't afford; when lenders push inappropriate loans on borrowers in order to generate origination fees; when banks don't explain to borrowers that in two years their interest rates will increase and their mortgage payments could double, then the links in the chain start getting pulled pretty tight.

When you can't afford your mortgage, you can try to sell your house and bail yourself out, but what if it isn't enough to pay back the mortgage? What if this started happening to thousands of people? Well it did. And when enough people can't pay back their loans, then a link in the chain breaks. Housing prices start decreasing, the packages of loans the investors bought from the banks is worth much less, and somewhere, whoever the investors borrowed money from to buy that package of loans wants their money back yesterday. That's when things get really dicey.

[As a detour, I would like to point out one market that has not failed: The microfinance market. In developing countries around the world, women (and a few men) are borrowing small amounts of money in numbers unimagined even a decade ago...and paying it back! When five women get together and say to each other, "if one of us fails, we're all responsible," that means something. There are many microfinance organizations to which you can donate, or even lend, money, but I will save that for another time.]

The social contract of borrower and lender in the U.S. has faltered, and as a result the trust we depend on that makes lending money possible has been severely impaired. And that is where we are today, an accelerating lack of trust: no trust for home mortgages, no trust for student borrowers, for Fannie Mae or Freddie Mac or the U.S. dollar. What is the U.S. dollar backed by? Not gold. Not diamonds. Not Warren Buffet. Our currency is backed by the full faith and credit of the United States Government.

Take note, because those words, "faith and credit," they go hand in hand. In order to believe in our economy, we must believe in our government. So, Government, pretty please, give us something to believe in.


Will the credit crisis reduce people to laundering money?

Related Posts: It's the economy, stupid; Don't forget about your pet; An economic recovery plan, in a cup; The R-Word; Penny Pinchin' Times


Wednesday, March 5, 2008

Higher Education in Danger for Bay State?

I'm a proud graduate of UMass-Amherst, along with two of my brothers. My little sister is currently attending UMass-Dartmouth. Thanks to hard work, scholarships, and my parents' savings, we were fortunate enough to attend college and graduate with minimal loans. Now I have a great job doing something I love - and this wouldn't have been possible without my college edu-ma-cation.

"Duh," you might say. "College gets you ahead."

However, young adults in the Commonwealth may not be as lucky as we were. This morning WBUR (my local NPR station) had a piece on how the non-profit Massachusetts Education Financing Authority has not been able to secure any funding for its low cost college loans programs. That's zero. Zilch. Nada. No money for their loan program, which has been helping out students for over 25 years.

Bob Oakes, the interviewer, seemed taken aback by this. "Not a dime?"

They were looking to raise close to $600 million for student loans, and blame the credit crunch for their difficulty. Various politicians have written letters to other politicians, but we all know where that will go: Nowhere.

As the director of MEFA said, this problem is going to have an immediate impact on Massachusetts. If students can't get funds, they won't be going to college, which will mean we will have a larger uneducated work force, and potentially a larger drain on social services. Students and their families may leave Massachusetts to live in other states where more funding may be available, or state schools are more affordable.

Can anyone say, "Brain drain?" Massachusetts, currently a state known for (and proud of) its well educated workforce, could be on the road to a big fat nowhere.

Did you get loans for college? What would you have done if the money just wasn't there?

Will there be fewer ecstatic graduates in Massachusetts in four years?

Thursday, January 31, 2008

An Economic Recovery Plan, in a cup.


Starbucks Corp., the world's largest chain of coffee shops has recently unveiled its economic recovery plan, further highlighting the compete inadequacy of our current leadership.

Acknowledging the fact that the Bush administration can’t independently handle the fiscal woes of our staggering economy, Starbucks throws its hat, or cup, into the ring. They hope that by offering the $1 Short Coffee they will help jump start the country's economic recovery. Those close to executive management said: “we would like to emphasize that our loyal customers can still enjoy grossly overpaying for our products if they choose."

I’m looking forward to the $1 coffee. And, as a side note, Starbucks has been great to
OYFP! They’ve donated their great coffee and baked goods to a few of our past events.

Saturday, January 19, 2008

What we don't know may kill us. Or not.

I'm glad John brought up the recession. It may actually have started already and we just don't know. Or it may never start, though the way things are going it's hard to imagine a big turnaround just around the corner.

The news topic of the week seems to be "what is the federal government going to do about the recession?" There will be much debate and perhaps some action, and later people will claim "this worked" and will be rebutted by "no, you're wrong, that worked." Meanwhile, many believe that congressional action can't work at all, and that these things are best left to the Federal Reserve, which can fix the problem more cleanly by simply cutting interest rates.

The funny thing about economics, though, is that no one really knows for sure what will work, or how quickly. Frankly, its status as a science can be a little on the murky side sometimes. It makes me sad because I really like economics, and I gravitate to the straight forward logic of (i) identify problem, (ii) find solution, (iii) implement solution, (iv) magic! But we have seen periods in which tax cuts were followed by economic growth and periods where tax increases were also followed by economic growth, as just one example. Go figure. Of course, that doesn't mean that nothing should be done. In fact, our quasi-ignorance probably means that a belt and suspenders approach is probably most appropriate.

But it's not just economics that's the problem. So many important public policy decisions are presented to us as clear imperatives (do this, don't do that)--war, health care, foreign aid, environmental issues--while meanwhile their vast ramifications are, more often than not, largely unknowable. I just wish we could all recognize how much we don't know, and that our civic leaders would consider more deeply what would happen if their plans for us, well, just didn't work out quite right.

Thursday, January 17, 2008

The R-word

Recession. Yes, I said it. And, I just might be contributing towards it… with this blog. “An interesting indicator, the “R-word” index” -- the number of stories appearing in print that use the word “recession” -- has spiked in early 2008.” According to The Economist, this simple tool has forecasted the start of the recessions in 1981, 1990 and 2001.

A recession occurs when the gross domestic product (GDP) declines for two or more consecutive quarters. The GDP is the value of all the reported goods and services produced in a country. Some market indicators that signal the onset of a current recession include: a spike in oil prices, the news of major financial companies taking huge losses due to subprime mortgage defaults, slumping home values, and consumers' purchasing power being lowered by high energy and food prices. If all this is happening, it's a good bet that companies have laid people off, so unemployment is up too.


There have been 11 recessions since 1945, and they are an expected part of the economic cycle. The National Bureau of Economic Research says that “the US economy follows a somewhat regular pattern of expansion and contraction. The economy will typically expand steadily for six to ten years and then enter a recession for six months to two years.”

Since it isn’t beneficial for a nation to be in recession, governments will normally take action to get the economy going again. Ben S. Bernanke, chairman of the Federal Reserve, recently stated that he supports tax cuts or other measures to stimulate the economy. It is widely anticipated that Federal Reserve will reduce interest rates at the Federal Open Market Committee meeting on Jan. 30. The New York Times reports that “on Wall Street, investors are betting that the central bank will reduce overnight lending rates to 3.75 percent from 4.25 percent.”

The R-word is here, Recession.

Related Posts: It's the economy, stupidWhat is this credit crisis you speak of, and why do I care?Don't forget about your petAn economic recovery plan, in a cup; Penny Pinchin' Times